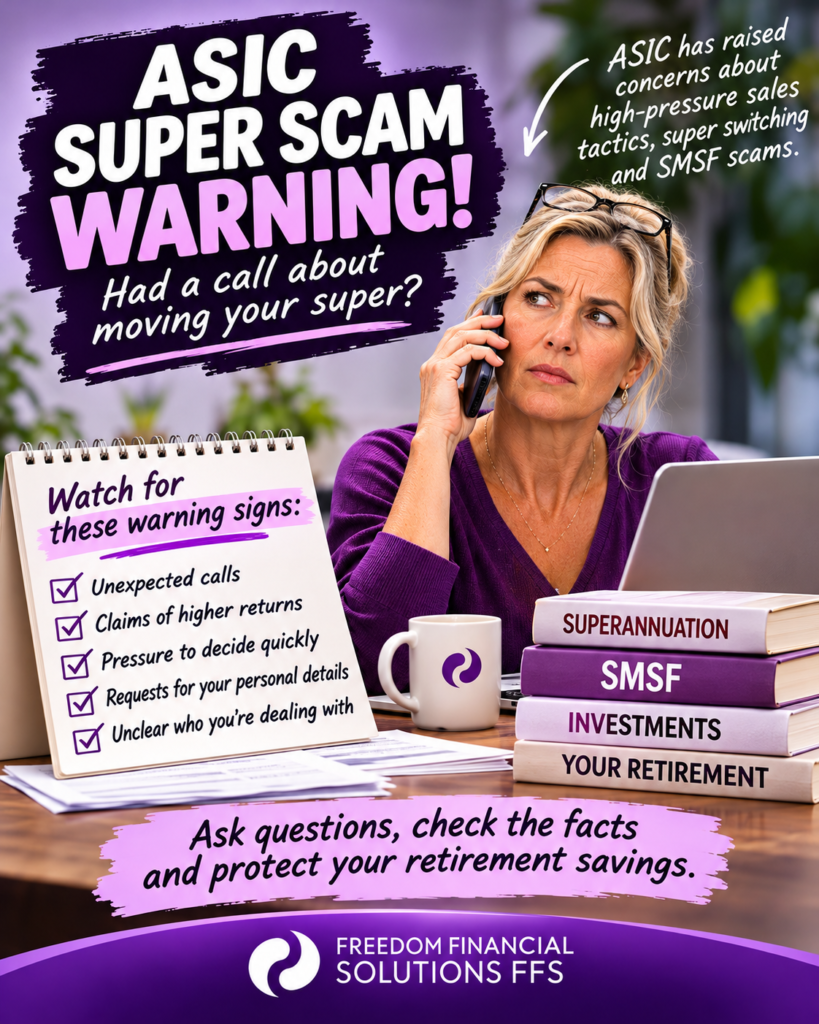
Unexpected calls, free super health checks and promises of better returns could put your retirement savings at risk. ASIC has raised concerns about high-pressure sales tactics encouraging Australians to switch super funds or establish self-managed super funds (SMSFs).
Have you received an unexpected phone call offering a free super health check?
Perhaps someone told you your super fund was underperforming, promised better returns elsewhere or suggested moving your retirement savings into an SMSF.
It might sound helpful. After all, who doesn’t want to make the most of their super?
But before you share your details or agree to anything, there’s an important question worth asking.
Who is really benefiting from you moving your super?
ASIC raises concerns about superannuation switching
ASIC has examined financial advice businesses using lead generation services to attract clients interested in switching superannuation funds or making new investments.
Its November 2026 review of 15 advice licensees identified approximately $678 million in switching and investment activity associated with referred clients, with around 90% involving superannuation savings.
The review also identified approximately $9.8 million in upfront advice fees and a further $4.5 million in agreed annual ongoing fees.
These figures do not mean that all the transactions were fraudulent or inappropriate. However, ASIC identified concerns about sales practices, potentially misleading representations and inadequate supervision of some lead generation arrangements.
The findings raise important questions about how Australians are approached to move their retirement savings and whether consumers understand the arrangements being promoted.
Read ASIC’s warning about lead generators and financial advice licensees.
How do these super sales calls work?
Some approaches begin with an unexpected telephone call. Others start when someone clicks a social media advertisement, completes an online quiz or requests a free superannuation health check.
These enquiries may be passed to businesses known as lead generators, which identify potential customers and connect them with financial services providers.
Lead generation itself is a legitimate marketing practice.
However, ASIC has raised concerns where salespeople become involved in discussing investment performance, recommending financial products or encouraging consumers to switch funds without the appropriate authorisation.
Some businesses may benefit financially when consumers switch super funds, establish SMSFs or purchase particular investment products.
That doesn’t automatically make the arrangement improper. But it does make it important to understand who you’re dealing with, what they’re offering and how they’re being paid.
Six warning signs to watch for
Not every unexpected call is a scam. But there are several warning signs that should prompt consumers to ask more questions.
1. An unexpected call about your super
Someone you don’t know offers a free super health check, performance comparison or assistance locating lost super.
Be cautious if you haven’t requested the contact, particularly if the caller asks for personal information.
2. Claims that your existing super fund is underperforming
You may be told that your current fund is delivering poor returns and that another arrangement could perform better.
Meaningful comparisons need to consider investment risk, fees, insurance and the differences between investment options.
3. Promises of higher returns
Be wary of claims that switching super funds or establishing an SMSF will automatically produce better investment returns.
An SMSF is a legal structure for managing retirement savings, not an investment that generates returns by itself.
Investment performance depends on the assets held, costs, investment decisions and market conditions.
4. Pressure to make a quick decision
You may be encouraged to sign documents or transfer money immediately, sometimes with claims that an opportunity is available for a limited time.
There should be sufficient time to understand what you’re agreeing to and consider the consequences.
5. Requests for personal information
A caller may ask for your super balance, income, date of birth, identification documents or account information.
Never disclose passwords, verification codes or account access details to someone who contacts you unexpectedly.
6. Unclear information about who is providing the service
You may speak with several people, including sales representatives, financial advisers and investment promoters.
Make sure you understand who is responsible for each service, whether financial advice is being provided and how the businesses involved are being paid.
Are SMSFs risky?
Self-managed super funds are a legitimate and established part of Australia’s superannuation system.
An SMSF allows members to take greater direct control over how their retirement savings are managed and invested.
For some Australians, that flexibility is an important consideration.
But greater control also comes with responsibilities.
SMSF trustees must ensure their fund complies with superannuation and taxation laws, maintains appropriate records, follows an investment strategy and meets ongoing reporting and audit obligations.
Establishing and operating an SMSF also involves costs that should be considered alongside the benefits and responsibilities.
The important distinction is between making an informed decision to establish an SMSF and being pressured into one to purchase a particular investment or service.
An SMSF is not automatically more suitable, less expensive or more profitable than an industry or retail super fund.
Different people have different circumstances, objectives and financial arrangements.
What could you lose by moving your super?
Changing super funds can have consequences beyond transferring your account balance.
Depending on your circumstances, you could:
Lose life insurance, total and permanent disability or income protection cover attached to your existing fund.
Pay different or higher administration and investment fees.
Move into investments with different risks or limited liquidity.
Lose access to particular benefits or services.
Take on additional legal and administrative responsibilities if establishing an SMSF.
Before making a decision, it’s important to understand both the potential benefits and what you might be giving up.
The ATO also warns about SMSF scams
The Australian Taxation Office has separately warned Australians about scammers who encourage people to establish SMSFs or move their super into fraudulent arrangements.
Some scammers impersonate legitimate financial services businesses, use stolen personal information or promote supposedly high-performing investments.
Others claim they can help Australians access their super early by establishing an SMSF.
In some cases, criminals obtain control of the fund or its bank account and steal retirement savings.
Establishing an SMSF does not allow you to access your super whenever you choose.
Superannuation remains subject to the legal conditions of release. Illegal early access can result in substantial tax consequences, penalties and the loss of retirement savings.
You can read more in ASIC’s guide to superannuation scams.
Five things to check before moving your super
If you’re considering changing your superannuation arrangements, take the time to understand your options.
1. Check who you’re dealing with.
Verify the business independently. If someone claims to provide personal financial advice, check their details on ASIC’s Financial Advisers Register.
2. Understand the costs.
Compare establishment, administration, investment and other relevant expenses. Lower fees in one area don’t necessarily mean lower overall costs.
3. Review your existing arrangements.
Check your current investment options, insurance cover, fees and benefits before transferring your savings.
4. Understand SMSF responsibilities.
If you’re considering an SMSF, learn about trustee obligations, investment strategies, compliance requirements and ongoing administration.
5. Don’t be rushed.
Never make significant financial decisions simply because an unsolicited caller or salesperson is pressuring you.
If you suspect someone is attempting to access your super fraudulently, contact your existing super fund immediately.
You can also report suspected scams to Scamwatch or contact the ATO on 13 10 20.
Your super. Your decision.
Australians have good reasons to take an active interest in their superannuation.
Understanding your investment options, reviewing fees and insurance, and exploring different superannuation structures can all be part of managing your retirement savings.
For some Australians, that exploration may include considering an SMSF.
But there’s a big difference between taking greater control of your super and handing control to someone whose motivations you don’t understand.
The bottom line? Ask questions, check the facts and make informed decisions. Your retirement savings are too important to be rushed.
Thinking about establishing an SMSF?
At Freedom Financial Solutions, we assist Australians with the administrative process of establishing an SMSF, including establishment documentation, corporate trustee arrangements where required, fund registration and rollover paperwork.
We also provide information about the establishment process, associated costs and ongoing responsibilities so you can better understand what’s involved.
If you’re exploring the possibility of an SMSF, understanding how the structure works is a useful starting point.
Learn more about SMSF setup with Freedom Financial Solutions.
Official sources
General information only. Not personal financial advice. This article does not consider your personal objectives, financial situation or needs. Consider seeking advice from an appropriately licensed financial adviser before making decisions about your superannuation.