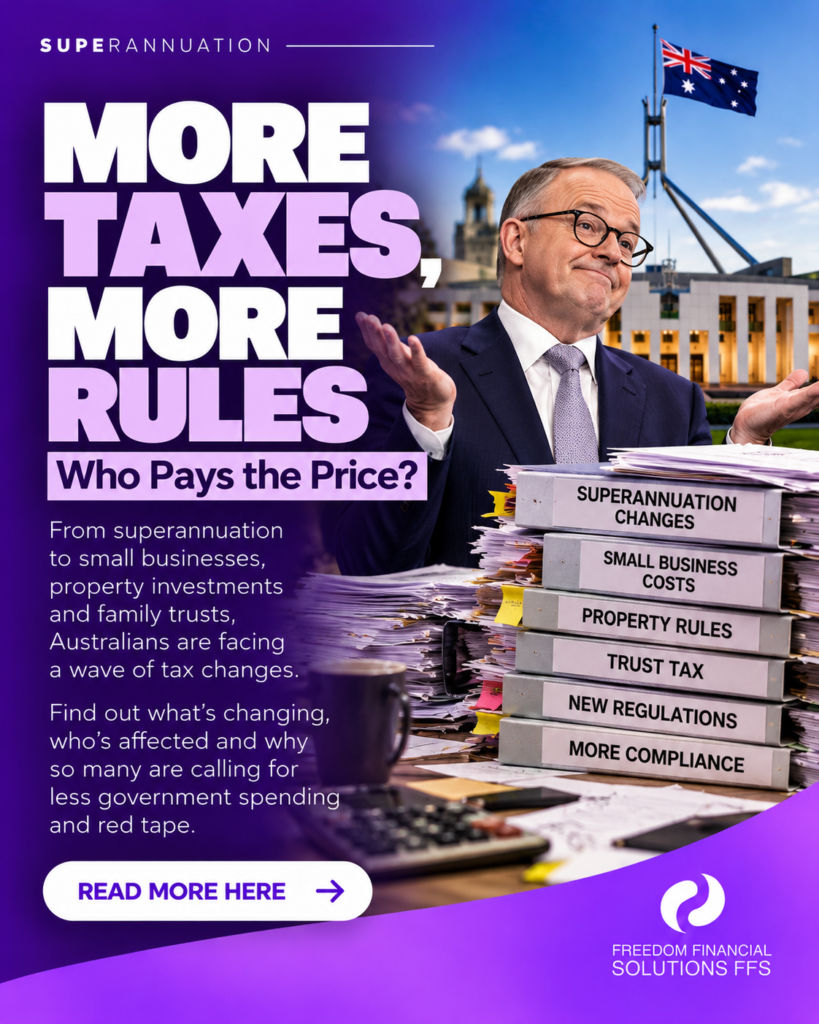
From superannuation and small businesses to property investments and family trusts, Australia is experiencing a major overhaul of its tax system. The government says the changes will make taxation fairer, but business groups are questioning the costs, complexity and consequences for everyday Australians.
How many changes to Australia’s tax and superannuation systems can people absorb before they start asking serious questions?
Small business owners are already dealing with rising costs, wages, insurance, payroll obligations and an ever-growing list of administrative responsibilities.
Now they are also navigating major changes to capital gains tax, investment property deductions, superannuation and proposed new taxes on family trusts.
Individually, each reform comes with an explanation about fairness, sustainability or improving the tax system. But taken together, they represent a substantial change to the rules affecting how Australians earn, invest, save and plan for retirement.
And business groups are pushing back.
Small businesses are making their voices heard
The concerns are no longer confined to accountants, tax advisers and financial industry specialists.
Small business organisations and industry representatives have questioned the potential costs of restructuring businesses, additional compliance obligations and the uncertainty created by multiple reforms occurring within a relatively short period.
For a large corporation, adapting to new tax rules might involve an internal finance department and specialist advisers.
For a small business, it can mean paying additional professional fees, changing accounting systems, managing cash flow and spending more time on administration instead of serving customers.
These are the builders, tradespeople, retailers, cafes, professional practices and family enterprises that employ Australians and contribute to their local communities.
Many have spent years building businesses, paying tax and making financial decisions under the rules that existed at the time.
When those rules change, the consequences can extend well beyond the amount of tax payable.
It is not just one tax change
The scale of the current reforms is what makes this debate particularly important.
Superannuation: Changes to the taxation of larger super balances and new employer superannuation payment requirements have prompted questions about retirement planning, compliance and business cash flow.
Capital gains tax: Legislation passed in June 2026 replaces the existing 50% capital gains tax discount with inflation-based adjustments and a minimum 30% tax on relevant real capital gains accruing from 1 July 2027. Existing small business capital gains tax concessions remain available to eligible businesses.
Investment property: New negative gearing rules will restrict deductions against unrelated income for certain established residential properties purchased after the May 2026 Budget announcement. Existing properties covered by the grandfathering arrangements and eligible new builds receive different treatment.
Family trusts: The government has introduced legislation proposing a minimum 30% tax on certain discretionary trust income from 1 July 2028, with exemptions and restructuring options.
Business administration: Payday Super and other reporting obligations require employers to review their payroll processes and cash flow management.
Some of these measures have already been legislated. Others, including the proposed discretionary trust minimum tax, are still being considered by Parliament.
Not every change will increase costs for every Australian. But even when a reform does not directly increase someone’s tax bill, understanding the new rules and updating existing arrangements can involve additional work and expense.
What about government spending and regulation?
The government says its reforms will make the tax system fairer and more sustainable.
But that raises another important question: what is being done to control government spending and reduce the cost of regulation?
Small businesses cannot simply increase their income whenever their expenses rise.
They must manage costs, improve efficiency, make difficult decisions and remain accountable for every dollar.
Government finances are more complicated. Public spending funds essential services, infrastructure, defence, health, education and other priorities that cannot always be reduced without consequences.
Nevertheless, questions about value for money, efficiency and accountability are legitimate.
Australia’s budget position, the cost of government programs and the administrative demands placed on businesses should all be part of the tax reform conversation.
Before introducing additional obligations, policymakers should be able to explain what existing expenditure has been reviewed, which regulations could be simplified and why new revenue measures are considered necessary.
For small businesses and everyday Australians, the debate should not be limited to how much tax the government collects.
It should also examine what government spends, what that spending achieves and how much compliance costs the people who fund it.
What is the government trying to achieve?
The government argues that its tax reforms are designed to make the system fairer and more sustainable.
Its position is that certain forms of investment income receive tax advantages that are not available to people earning ordinary wages.
It also says the changes will support housing supply and help fund tax relief for working Australians.
The broader reform package includes measures intended to benefit small businesses, including a permanent $20,000 instant asset write-off, tax loss relief and the retention of existing small business capital gains tax concessions.
The government estimates that more than 90% of active small businesses will not be affected by the proposed discretionary trust minimum tax in any given year.
These measures and estimates are important to consider.
However, business representatives are entitled to question whether the benefits outweigh the costs for businesses that are affected, particularly when additional administration, professional fees and long-term planning consequences are taken into account.
A reform can have a legitimate objective and still create unintended problems in practice.
When does tax reform become too much change?
For ordinary Australians, financial planning often involves decisions made over decades.
A family might establish a business with the intention of passing it to their children. Someone might purchase an investment property to help fund retirement. Others might choose an SMSF because they want greater control over how their superannuation is invested.
These decisions can involve years of work, saving and financial commitment.
When tax rules change, people may need to revisit arrangements they reasonably expected to maintain for many years.
That does not mean tax rules should never change. Governments need to respond to economic conditions, changing circumstances and concerns about fairness.
But it raises legitimate questions about how much change should occur at once, whether the practical consequences have been properly considered and whether Australians have enough time to adjust.
A fair tax system should also be understandable, predictable and reasonably affordable to comply with.
Australians are paying attention
One positive development is that tax and superannuation policy is becoming a more visible public conversation.
Small business organisations are speaking publicly about proposed reforms. Accountants and industry bodies are examining the details. Investors and superannuation members are asking questions about what the changes mean for them.
The debate is not one-sided. Some Australians support reforms they believe will make taxation fairer, while others are concerned about higher costs, reduced flexibility and uncertainty.
What matters is that people understand the rules affecting their financial future and have an opportunity to contribute to the discussion.
Importantly, some changes are not yet law
One point deserves particular attention.
The proposed 30% minimum tax on discretionary trusts has not yet been legislated.
The government introduced the relevant bills into Parliament on 14 October 2026, with the proposed changes intended to commence on 1 July 2028.
The legislation remains subject to parliamentary consideration and could still be amended.
Other elements of the broader reform package, including major capital gains tax changes, have already passed Parliament.
Understanding the difference between a proposal, an announced reform and an enacted law is essential before making financial decisions.
It is not too late to have your say
Australians who are concerned about proposed tax changes can participate in the democratic process while legislation is being considered.
The Senate inquiry examining the discretionary trust legislation is accepting submissions until 29 October 2026.
Individuals and businesses can explain how proposed changes might affect them, raise concerns about unintended consequences or suggest practical alternatives.
You do not need to be a tax expert to describe the realities of operating a small business, managing investments or planning for retirement.
People can also contact their federal MPs and senators about tax and superannuation policy more broadly.
Whether you agree with the reforms, disagree with them or believe they need improvement, informed participation helps ensure that practical consequences are considered.
Your financial future deserves your attention
Tax and superannuation rules are not just matters for politicians, accountants and financial institutions.
They affect how businesses operate, how investments are taxed, how retirement savings are managed and what families can pass on to the next generation.
The current debate raises questions that deserve serious consideration.
Are the changes necessary? Are they fair? Have the costs been properly assessed? And has enough been done to control government expenditure and reduce unnecessary regulation?
These are questions Australians are entitled to ask, regardless of their political views.
Some reforms are already law. Others are still being considered. And where decisions have not yet been finalised, there is still an opportunity to contribute to the discussion.
Understanding what is changing is the first step towards making informed decisions about your business, investments and financial future.
Find out more about current legislation and parliamentary inquiries at aph.gov.au.
Sources and further reading
Treasury: Capital Gains Tax and Discretionary Trusts Reform, Small Business Explainer
Australian Government: What the Budget Means for Your Business
Treasury Ministers: Tax Reform for a Fairer Tax System, 14 October 2026
This article provides general information only and does not constitute personal financial, tax or legal advice. Proposed legislation may change, and individual circumstances will determine how particular reforms apply.