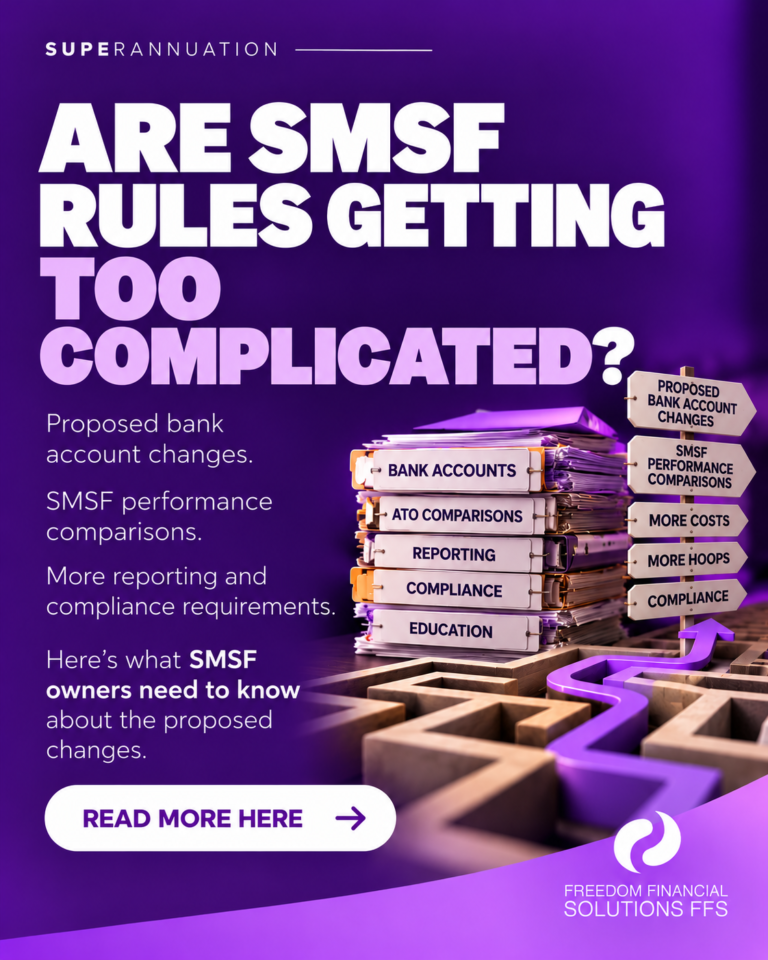
How many hoops should Australians have to jump through to manage their own super?
Could your SMSF face new bank account requirements? Could the ATO start comparing your investment returns with those of large super funds? These are two of the changes the government is proposing, and the SMSF Association has raised concerns about how they could work in practice.
First, new bank account requirements. SMSFs already need their own bank accounts, separate from personal or business finances. But the government now wants SMSF bank accounts to be uniquely identifiable under additional requirements. The industry is asking for clarification, particularly about whether SMSFs will still be able to operate multiple bank accounts.
Second, comparisons of SMSF investment performance. The government wants the ATO to give SMSF owners, particularly those with smaller balances, more information about how their investment returns compare with larger super funds.
Sounds reasonable, doesn’t it? But consider someone who has just established an SMSF. Their money might be sitting in cash while they wait for rollovers, research investments or prepare to purchase a property. Comparing their returns with a large super fund at that point could give a very misleading picture.
Third, investment strategies at setup. SMSFs already need an investment strategy, but the government is proposing that new funds have a written strategy in place upfront. The details are still unclear, including whether the ATO would receive or review these strategies as part of registration. And that’s raising some practical questions. How detailed must your investment plans be before you’ve even rolled over your super? What if you’re still researching your options or your plans change? The SMSF Association has questioned what the ATO would actually do with this information.
And these aren’t the only changes on the table. The government is also proposing mandatory education for new SMSF owners, greater ATO powers to stop certain rollovers, additional reporting and higher supervisory levies.
Each proposal has a stated purpose, whether that’s preventing fraud, improving transparency or protecting retirement savings. We’re all for protecting people’s super, and education is important too.
But what happens when you add them all together?
Another rule, another requirement, another cost and another hoop to jump through. At what point does managing your own super become so complicated that ordinary Australians simply decide it’s all too hard?
Nobody is suggesting SMSFs should operate without rules. We’re talking about people’s retirement savings, after all. But those rules also need to be practical, proportionate and fair, without making it unnecessarily difficult for Australians to manage their own money.
Importantly, these changes are still proposals, not new rules already in force. The details may change before they become law, so there’s no need to change your SMSF arrangements simply because they’ve been announced.
For now, the best thing SMSF owners can do is stay informed and understand what’s actually changing. There’s already enough to think about when managing your own super without worrying about rules that haven’t even been introduced yet.
They make the rules. We help make them simple to follow.
At Freedom Financial Solutions, we help Australians understand and manage the accounting, tax, compliance and administration requirements of their SMSFs.
Learn more about SMSFs at Freedom Financial Solutions
General information only. This article does not constitute financial or legal advice.