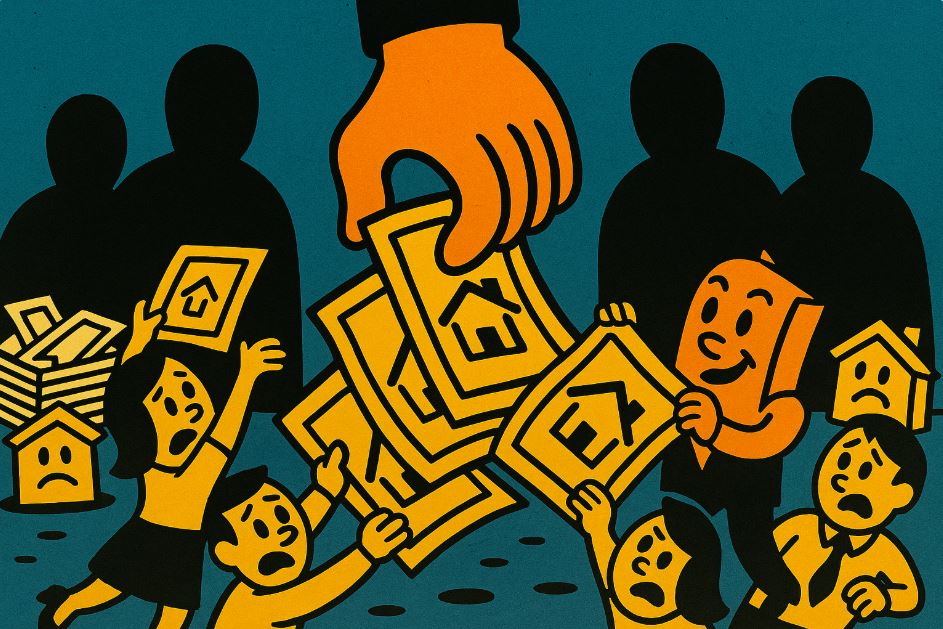
Ever thought someone had your best interests at heart? Think again. David Webb’s The Great Taking reveals the uncomfortable truth about how the financial system is rigged—benefiting a select few while leaving everyday Australians vulnerable. From superannuation to property rights, the very foundations of personal wealth and financial security are being undermined by global financial institutions and manipulated policies. It’s time to face reality: the game is being played, and most of us are losing.
In this article, we’ll break down the key insights from Webb’s book, explaining how the concentration of wealth and power in the hands of a few is affecting your financial future. We’ll also explore strategies that Australians are using to protect their wealth and ensure they’re not left behind in the next financial crisis.
Financial Manipulation and Market Distortion
The financial system is increasingly manipulated by a small group of powerful institutions, distorting market realities for the benefit of a few:
Impact of Central Bank Policies: Central banks, particularly through their control over the money supply, are manipulating markets in ways that benefit large institutions at the expense of individual investors. Webb argues that central bank policies are key drivers of economic instability and market distortions.
Market Volatility and Hedge Fund Management: Webb successfully navigated market volatility by developing methods to anticipate changes based on money supply growth. His hedge fund experience revealed patterns that allowed him to grow wealth during times of crisis, but it also exposed the deep flaws in the system, where the game is rigged in favor of big players.
Implications for Australians
Australians should be aware of the risks posed by central bank policies and market manipulation. The Australian economy is tied to global financial trends, and while local central banks may not have direct control over global markets, they can influence domestic conditions. This could lead to higher costs of living, inflation, and the devaluation of savings.
To mitigate these risks, many Australians are turning to alternative assets that are less affected by market distortions, such as gold, property, or other tangible investments.
The Decline of Traditional Ownership and Property Rights
One of the key points Webb makes is the steady erosion of traditional ownership in the financial system, replaced by a more complex and precarious system of security entitlement:
Security Entitlement: Webb introduces the concept of “security entitlement,” which replaces traditional ownership with a claim against a financial institution holding your assets. In practice, this means individuals no longer truly “own” their assets. Rather, they have a claim on the assets, which are pooled together and treated as collateral for larger financial transactions.
Legal and Structural Shifts: The transition to a system where pooled securities are used as collateral erodes individual ownership. During times of financial distress, individuals could lose their assets to creditors, receiving only a pro-rata share, leaving them vulnerable in the event of a custodian’s insolvency.
Implications for Australians
With the increasing financialization of assets, Australians should be particularly cautious about how their wealth is held—especially within superannuation and investment portfolios. The shift from real ownership to a claim on assets means that Australians may not have as much control over their property and savings as they believe. This change is particularly concerning in the context of property rights.
Property Rights Under Threat: Webb discusses how property rights have been undermined by the movement toward treating assets as collateral for financial institutions. The notion of true ownership is increasingly being replaced with a legal claim on assets, where properties can be pooled and used to back financial transactions. This shift puts Australian homeowners and investors at risk—especially if those holding these assets (banks, custodians, or central clearing parties) face financial instability or insolvency.
In light of this, many Australians are now looking to safeguard their wealth through tangible assets such as physical property or precious metals. However, this strategy comes with its own risks. The subversion of property rights means that owning property is no longer as secure as it once was. While real estate has traditionally been a stable investment, the increasing trend to treat property as collateral in the broader financial system exposes it to the same risks faced by other financial assets. In the event of financial collapse, individuals may find their homes and investments at risk, with creditors able to seize them.
Diversification and Security: To avoid falling victim to this shift in property rights, Australians are being more strategic about their investments. Many are moving beyond just property to include assets that are harder to control or seize—like gold and other precious metals. These tangible, non-digital assets are seen as a safer way to protect wealth from the growing concentration of power in the hands of large financial institutions.
The Global Financial Crisis and Systemic Risks
Webb warns that financial crises are not only predictable but are also driven by systemic flaws in the global financial system:
The Prelude to the 2008 Financial Crisis: Webb identified early signs of economic distress before the 2008 financial collapse. Increased foreclosures, utility delinquencies, and the manipulation of foreclosure data all pointed to a financial crisis. Webb criticized the Federal Reserve for inflating financial assets while ignoring the real economy, which led to widespread instability.
Asset-Backed Securities and Financialization: Webb successfully predicted the rise of asset-backed securities (ABS) and their role in causing the next financial crisis. As financial assets became increasingly “securitized,” they were treated as collateral, increasing systemic risk. This shift towards financialization, where assets are no longer managed for their inherent value but are used as leverage in financial markets, has concentrated wealth and power in the hands of a few large institutions.
Implications for Australians
Australians should be aware that another financial crisis could be on the horizon, and the economic conditions that led to the 2008 global financial crisis still exist in various forms. Asset-backed securities, excessive debt, and the unchecked power of financial institutions remain present risks.
Many Australians are taking steps to prepare for financial uncertainty by ensuring their wealth is protected through strategies that limit exposure to market volatility. This includes diversifying investment portfolios and staying informed about the global financial situation.
The Subversion of Property Rights and the Legal Landscape
The erosion of property rights, especially through new financial instruments, is one of the most troubling aspects of the modern financial system:
Legal Certainty and Collateral Management: Webb critiques efforts to harmonize laws regarding securities and collateral across borders, which ultimately shift the focus from individual property rights to the needs of secured creditors. These changes were particularly evident in the Euroclear system, where securities are pooled and treated as collateral, weakening individual ownership and exposing investors to greater risks during financial turmoil.
Changes in Property Rights in Sweden and Finland: Webb highlights how countries like Sweden and Finland transitioned their legal systems to allow securities to be pooled, undermining traditional property rights. The legal changes in these countries have made it easier for central depositories to seize assets during a financial crisis, leaving individual investors exposed.
Implications for Australians
Australians need to be vigilant about the risks posed by the erosion of property rights in financial systems. With more financial instruments being used as collateral, it’s crucial to understand that ownership is becoming less clear-cut. Many Australians are turning to tangible assets to maintain more control over their financial futures and protect their wealth from being used as collateral without their knowledge or consent.
The Role of Central Clearing Parties (CCPs) and Systemic Risk
Central Clearing Parties (CCPs) play a crucial role in financial markets by assuming counterparty risk and clearing trades. However, Webb identifies several key risks associated with CCPs:
Concentration of Risk: CCPs manage large portions of market risk, especially in derivatives and complex financial products. This concentration increases the potential for systemic collapse if a CCP were to fail, putting the entire financial system at risk.
Regulatory Reforms and Financial Stability: While regulators are working to create recovery and resolution frameworks for CCPs, Webb emphasizes that the concentration of risk within these institutions is a major threat to financial stability. If a CCP were to collapse, it could trigger a cascading failure of the global financial system.
Implications for Australians
While Australia’s financial system may not be as directly reliant on CCPs as other countries, the risks posed by centralized financial institutions and interconnected markets still affect Australians. In the event of a global financial breakdown, Australian investors could face significant exposure to market shocks.
Diversification is a strategy many Australians are embracing, looking to hold non-financial assets and prepare for potential instability by seeking independent financial advice.
The Global Shift in Legal Frameworks for Securities and Collateral
Webb critiques the movement toward a financial system that treats securities as collateral, shifting away from traditional ownership:
The Hague Convention and Cross-Border Legal Certainty: Webb explains that international efforts like the Hague Convention have aimed to establish legal certainty for cross-border securities transactions. However, these efforts have favored secured creditors at the expense of individual ownership rights, allowing for the manipulation of assets across borders without regard for the rights of individual investors.
The Safe Harbor Provisions in Bankruptcy: The U.S. Bankruptcy Code was amended in 2005 to establish “safe harbor” provisions that protect secured creditors during bankruptcies. These provisions allow for the transfer of customer assets without proving equivalent value, giving large financial institutions priority over smaller investors during a bankruptcy.
Implications for Australians
The shift toward global legal systems that prioritize secured creditors over individual property owners could impact Australian investors if similar changes are implemented locally. Australians are advised to stay informed about legal changes and take steps to protect their assets from being used as collateral without their explicit consent.
Conclusion: What Australians Are Doing to Protect Themselves
The insights from The Great Taking present a stark picture of a financial system rigged to benefit a select few, leaving everyday Australians vulnerable. However, many are adopting strategies to safeguard their wealth and secure their financial future. Here are some practical approaches being taken by individuals in response to these challenges:
Diversifying Investments: Many Australians are choosing to spread their wealth across tangible assets such as property, precious metals, and other non-digital assets. This approach helps reduce their reliance on the traditional financial system and protects them from market volatility.
Understanding Financial Products: A growing number of Australians are taking a closer look at how their superannuation and other investments are structured, ensuring they understand the risks involved. Some are working with independent financial advisors to help them navigate complex financial landscapes and protect their wealth from potential systemic risks.
Staying Informed: Increasingly, Australians are staying up to date with global financial trends and how they could impact the local economy. Many are actively educating themselves on financial market changes and potential policy shifts, ensuring they are better prepared to make informed decisions.
Advocating for Stronger Property Rights: As concerns about property rights grow, some Australians are supporting initiatives and policies that aim to safeguard individual control over assets. There is a growing movement pushing for stronger protections against the erosion of property rights and the use of personal assets as collateral without explicit consent.
By adopting these strategies, Australians are taking proactive steps to prepare for financial uncertainty and reduce their exposure to risks that may arise from the evolving financial system.
Cass and Carl will be chatting about this and more on Voice of Freedom, 6:30pm Thursday 14 August . Be sure to tune in to watch! Click here to watch live or here to rewatch the recording.