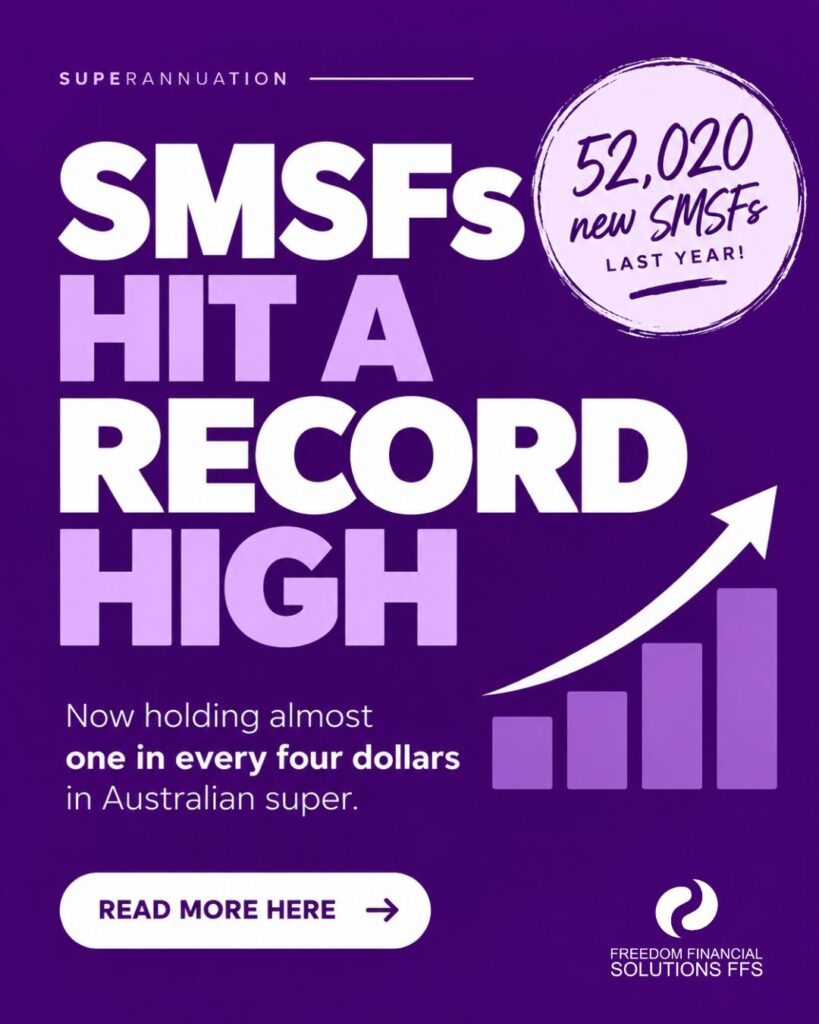
Something interesting is happening in super. Australians established 52,020 new self-managed super funds in the 2025-26 financial year, the highest number ever established in a single financial year, taking the total number of SMSFs to a record 680,301.
And these aren’t small numbers when you look at the super system as a whole. Australia had around $4.77 trillion in superannuation assets at 30 June 2026, with $1.107 trillion, or around 23%, held in SMSFs. In other words, almost one in every four dollars in Australian super is now held in the self-managed sector.
The latest Class 2026 Annual Benchmark Report gets even more interesting when you look behind those headline numbers, because the people establishing SMSFs may not be quite who you imagine.
SMSFs aren’t just for people approaching retirement
There is still a perception that an SMSF is something people think about when they’re in their late 50s or 60s and have accumulated a large amount of super. The numbers tell a different story.
Gen X and Millennials accounted for 89.1% of newly established SMSFs in FY26. The average age of a member establishing a new Class SMSF was just 47, compared with an average and median age of 62 across the broader SMSF population.
Class’s earlier half-year data had already identified the shift towards younger trustees, including the beginnings of Gen Z appearing in the establishment numbers. So while SMSFs remain an important retirement structure for many older Australians, the latest figures show they are increasingly being established earlier in people’s working lives.
And they’re bringing significant super with them
You might also assume younger SMSF members are starting with relatively small amounts, but again, the data is interesting. Newly established Class SMSFs had an average balance of $467,000 in FY25, while between FY23 and FY26, members establishing SMSFs consolidated an average of $267,000 through 1.5 rollovers.
There is also a lot of money moving. Over those four years, $14.4 billion was rolled into Class SMSFs, compared with $5.7 billion rolled out, with industry super funds accounting for 57.2% of the value rolled into SMSFs.
Of course, money moves the other way too. When SMSF members rolled money back into another super fund, retail funds received 66.7% of the rollover value, which is a useful reminder that an SMSF doesn’t necessarily have to be forever.
Class looked at 4,688 SMSFs that wound up during FY25 and found 51% didn’t roll over to another super fund at all. Class says this may reflect people leaving the super system through retirement withdrawals, death benefit payments or other benefit withdrawals. Of those that did move to another super fund, retail platforms were the most common destination.
Property was bigger than previously thought
One of the most interesting findings comes at a particularly significant time. Class identified 3,672 new residential property limited recourse borrowing arrangements (LRBAs) in FY25, an increase of 46.8% from FY23.
Almost one-third were associated with newly established SMSFs, while around two-thirds were established by existing SMSFs. Class estimates that approximately 11,500 new residential property LRBAs may have been established across the SMSF sector in FY25, compared with the ATO’s updated estimate of around 8,700 for FY24.
Class cautions that its figure is an estimate extrapolated from its own data and that there are limitations in the underlying LRBA data. Nevertheless, it gives us an interesting picture of how significant residential property borrowing had become within the SMSF sector before the recent changes affecting new residential property LRBAs.
Residential property also overwhelmingly dominated SMSF borrowing, accounting for 92.7% of Class SMSF LRBA holdings in FY25.
What are newer SMSFs investing in?
Earlier Class research also gives us a glimpse into what happens after a new fund is established. New SMSFs initially held a relatively large amount in cash and term deposits, at 35.9% of assets, followed by direct property at 23.3% and Australian equities at 10.7%.
That high cash figure isn’t necessarily surprising. Establishing the fund and rolling the money across is one thing, while actually implementing the fund’s investment strategy can take time.
ETFs are also becoming more visible. In the Class half-year data, 18.2% of newly established SMSFs held ETFs, although ETFs represented an average of only 7.7% of their assets.
Then there’s the $3 million question
The report also provides some interesting numbers around the new Division 296 tax. As at 30 June 2026, 8.8% of Class SMSFs had at least one member with a balance above $3 million, while another 9.4% had members with balances between $2 million and $3 million.
Class also found that 72.8% of SMSFs had a positive net unrealised capital gain position. Among funds with at least one member above $3 million, that increased to 95.4%, making accurate valuations, records and cost-base information particularly important for members affected by Division 296.
So why are SMSFs growing?
This is where we need to be careful not to make the statistics say something they don’t. The numbers don’t tell us that an SMSF is better than an industry or retail super fund, and they don’t tell us why every individual decided to establish one.
What they do tell us is that more Australians are establishing SMSFs, people are establishing them younger, and substantial amounts of super are moving into the sector. The growth over just 12 months is particularly striking: 42,336 new SMSFs were established in FY25, rising to a record 52,020 in FY26.
There may now be another factor influencing establishment numbers from here. The Government has announced plans to introduce basic trustee knowledge requirements before a new SMSF can be registered, although the detail and timing are still to be worked through.
At Freedom Financial Solutions, we’re already hearing from some people who are considering establishing an SMSF sooner because they would prefer to do so before any new education requirement begins. That’s anecdotal rather than evidence of a broader industry trend, but with establishments already at record levels, it will be interesting to see whether the proposed changes add further momentum before they commence.
For anyone considering an SMSF, establishment numbers are only part of the picture. SMSF trustees take on additional responsibilities for the operation and compliance of their fund, and different superannuation structures have different features, costs and obligations.
But the scale of the sector is worth putting into perspective. More than 680,000 SMSFs now hold around 23% of Australia’s entire superannuation pool, and younger generations accounted for the overwhelming majority of newly established funds in FY26.
Whatever is driving individual decisions, self-managed super is certainly no longer a small corner of Australia’s superannuation system.
This information is general in nature and does not take into account your personal objectives, financial situation or needs. Freedom Financial Solutions is not licensed to provide financial product advice under the Corporations Act. You should consider obtaining advice from an appropriately licensed financial adviser before making a decision about a financial product.
Sources: Class 2026 Annual Benchmark Report and associated Class Benchmark Report data, September 2026; Australian Taxation Office SMSF statistics; APRA Quarterly Superannuation Statistics, June 2026.